Account setup and verification guide
Kingmaker Registration and KYC: Account Setup for Australian Users
 Available in US
Kingmaker requires a personal account for full use of its website, and its terms set clear rules around account ownership, age and identity checks. Customers must be at least 18, register in their own correct name and keep account details accurate. The operator can request identity, residence, source-of-funds and payment-method evidence as part of KYC, including before or after deposits and before a withdrawal is completed. The current terms also give a formal response window: requested documents and information must be supplied within 30 days, while Kingmaker says it will usually review a complete response within 10 days, although more time can be needed in complex cases. Registration itself and later KYC are separate stages, so completing the sign-up form does not mean every verification check has already been satisfied.
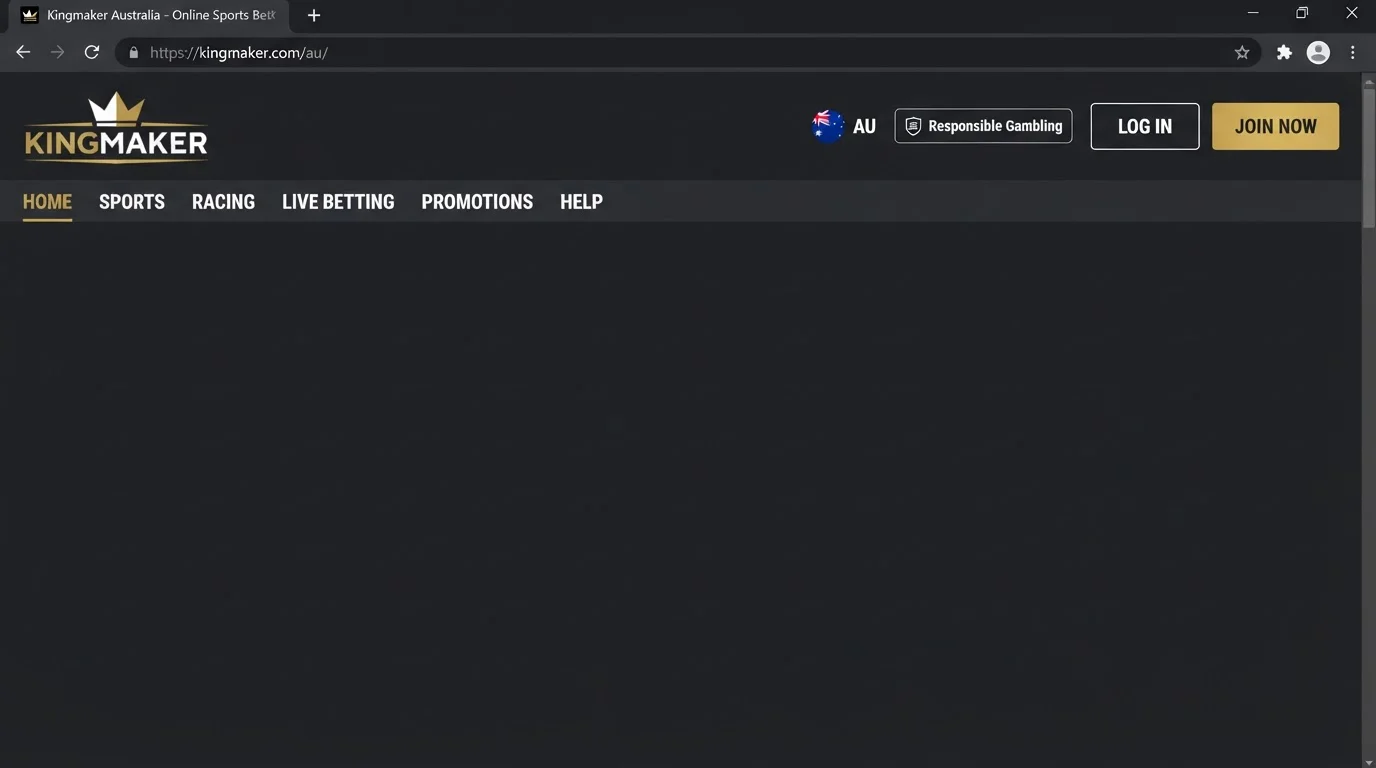
Table of Contents
- Registration creates one personal account, not a shared household profile
- The age rule is straightforward: 18+ is a Kingmaker account condition
- What the current KYC terms actually allow Kingmaker to request
- The terms set both a customer deadline and a normal review period
- Registration and KYC are separate stages
- Use consistent personal and payment information from the start
- Support is built into the account flow
- KYC can affect withdrawals without changing the underlying balance rules
- Bonus activation is another reason to keep account actions deliberate
- A practical registration and verification sequence
- What account verification does not prove
- The key account decision is whether the verification rules are acceptable before depositing
Registration creates one personal account, not a shared household profile
Kingmaker’s terms say the account must be registered in the customer’s own correct name. They also limit accounts by person, household or address, phone number, email address and IP address. That is more than a simple anti-duplicate rule: it means the safest registration approach is to use genuine personal details from the start and avoid creating a second profile to solve a forgotten-password, bonus or payment problem.
The operator treats additional profiles as duplicate accounts and reserves the right to close them. Its terms also say registration information must remain current, so changes to important account details should be corrected rather than worked around through a fresh sign-up. That matters later because identity checks compare the account record with the documents or payment evidence supplied during verification.
For readers looking at Kingmaker as a whole rather than only the account flow, the full review places registration alongside games, payments, mobile access and regulatory context.
The age rule is straightforward: 18+ is a Kingmaker account condition
Kingmaker states that its services are for people who have reached the legal age applicable to them and are at least 18 years old. Its AU-facing pages also display an 18+ statement. This is an operator rule for opening and using an account; it should not be confused with proof of an Australian gambling licence.
That distinction is important in Australia. An age gate can show that a website has a minimum-age policy, but it does not tell a reader whether the operator is licensed locally or whether a particular service may legally be provided to customers in Australia. Those are separate questions covered in the licensing and regulation.
From an account-management perspective, the practical consequence is simple: a person under 18 should not register, and false date-of-birth information creates an obvious mismatch if identity documents are later requested.
What the current KYC terms actually allow Kingmaker to request
Kingmaker’s current general terms are unusually specific about the categories of verification evidence it can request. They state that customers must provide information required to manage the account, verify identity or verify the source of deposited funds. The examples include properly certified identification, proof of residence, proof of ownership and transaction histories for payment methods, plus bank or credit or debit card statements.
The same terms allow additional checks for identity, age, residence and other circumstances. They also mention possible phone calls, face verification and other security checks where needed. These are not promises that every customer will be asked for every item. They define the evidence and procedures the operator may use when a particular account is selected for verification.
That difference is useful when preparing for KYC. A reader does not need to assume that every document category is mandatory in every case, but should expect the account name, residence and payment trail to be capable of verification. A payment method that belongs to somebody else is especially problematic because Kingmaker separately requires the card or other funding method used on the account to belong to the customer.
The terms set both a customer deadline and a normal review period
Kingmaker says requested documents and information must be supplied within 30 days after the request. It also states that payment can be withheld or an account suspended until the requested material is provided, and that failure to provide it in time can lead to permanent account closure.
Once a request has been answered in full, the terms say documents and information are usually verified within 10 days. That is not an absolute turnaround guarantee. Kingmaker expressly reserves the possibility of additional time or checks depending on the circumstances and complexity of the case.
Those two periods refer to different parts of the process. The 30-day period concerns how long the customer has to provide the requested evidence. The 10-day statement concerns Kingmaker’s usual verification period after the request has been answered completely. Sending incomplete files can therefore prevent the review clock from functioning as a simple ten-day countdown.
Registration and KYC are separate stages
The presence of a Register button on the AU site should not be read as evidence that full KYC takes place before an account is created. Kingmaker’s terms allow identity and related checks both before and after deposits and around withdrawals. That structure means a customer can encounter further verification after the initial sign-up has already succeeded.
This is common in account systems where basic registration captures personal and login information first, while higher-risk activity triggers later checks. For Kingmaker, the terms specifically connect verification with identity, age, residence, source of funds and payment ownership. The operator can also delay a withdrawal while those checks are incomplete.
Readers mainly concerned with the cash-out stage should use the separate guide to withdrawal verification, which keeps the payment rules distinct from general account setup.
Use consistent personal and payment information from the start
The simplest way to reduce avoidable account friction is consistency. The registration name should match the identity evidence that could later be requested. Address details should be kept current. The payment method should belong to the account holder, and the account should not be shared or transferred to another person.
These points follow directly from Kingmaker’s terms rather than from a generic KYC checklist. The terms say the account must be in the user’s own correct name, registration information must be true and complete, and payment instruments used to fund the account must belong to that user. They also prohibit selling, transferring or acquiring another person’s account.
This is also why a new account is a poor fix for a technical problem. If a login fails or an email address needs attention, support is the better route. Creating another profile can turn a simple access issue into a duplicate-account issue.
Support is built into the account flow
Kingmaker advertises 24/7 Live Chat for registered users and publishes the support address [email protected]. The AU site also directs registration questions to the support team. English is supported, so an Australian user does not need to rely on translated correspondence for ordinary account issues.
Live Chat is the more immediate route for a login, registration or navigation problem. Email is more suitable when the issue needs a written record or when documents, account closure or a detailed explanation are involved. The terms specifically name the support email for account closure and self-exclusion requests.
For deposit choices and payment categories rather than identity checks, the deposits and payments covers the cashier side of the account in more detail.
KYC can affect withdrawals without changing the underlying balance rules
Kingmaker’s terms say it can delay a withdrawal while checking identity, account balance, source of funds and compliance with the rules. This is the clearest connection between KYC and cash-out. A pending identity check is therefore not the same thing as a payment method being unavailable or a withdrawal automatically being rejected.
The useful distinction is between eligibility and processing. First, the account must satisfy the applicable terms, including verification when requested. After that, the withdrawal still follows the operator’s payment rules and any limits that apply to the account. Mixing those two stages can make it difficult to understand why a payment remains pending.
If a verification request arrives, the most productive response is to identify exactly what category of evidence is being requested and provide complete, readable material through the channel Kingmaker specifies. The terms allow broad KYC checks, but they do not imply that every account will follow an identical document sequence.
Bonus activation is another reason to keep account actions deliberate
Registration may lead directly into a welcome-offer flow, but the bonus terms are separate from KYC and account ownership rules. A customer should read the current promotion conditions before activating anything, especially because withdrawal requests can interact with bonus eligibility and wagering requirements.
The new-player bonus explains the current welcome package and its terms. Keeping the two topics separate helps avoid a common mistake: treating identity verification as a bonus condition or assuming that successful KYC automatically means a promotion can be withdrawn without its own wagering requirements.
Account verification establishes who is using the account and whether requested evidence has been supplied. Bonus rules determine what must happen to promotional funds. Both can matter before a cash-out, but they solve different problems.
A practical registration and verification sequence
- Open the official AU route and use the current Register control rather than a lookalike domain or third-party app.
- Enter accurate personal details and create only one account.
- Confirm that the name and address used on the account can be supported by genuine documents if KYC is requested.
- Use payment methods that belong to the account holder.
- Keep registration data updated instead of opening another profile after a change.
- If Kingmaker requests verification, read the request carefully and supply the requested evidence within the stated 30-day period.
- Allow for the stated usual review period after a complete response, while recognising that complex cases can take longer.
- Use 24/7 Live Chat or [email protected] when the account flow, documents or login instructions are unclear.
This sequence does not guarantee approval, because Kingmaker retains discretion to apply additional checks. It does, however, reflect the operator’s published account and KYC terms rather than assumptions about what a casino registration process normally looks like.
What account verification does not prove
Passing KYC proves neither local licensing nor that every service offered on the website is lawful to provide in Australia. Identity verification is an operator control. Australian regulatory status is a separate issue and should be assessed from ACMA and the federal legal framework, not from whether a registration form accepts an Australian user.
That separation is particularly important for Kingmaker because the AU-facing site is accessible and has an account flow, while ACMA has also published enforcement material concerning King Maker. The existence of one fact does not cancel the other. Registration evidence describes how the account system works; regulatory evidence describes the provider’s legal position in Australia.
The key account decision is whether the verification rules are acceptable before depositing
Kingmaker gives readers enough published information to understand the core account obligations before funding an account: one genuine personal profile, an 18+ minimum, truthful registration data, payment-method ownership and the possibility of identity, residence and source-of-funds checks. It also publishes meaningful KYC timing language rather than leaving the process completely undefined.
The strongest practical approach is to decide whether those requirements are acceptable before depositing. That avoids treating KYC as an unexpected obstacle only after a withdrawal has been requested. It also makes support conversations easier because the account record, payment ownership and verification evidence begin from the same consistent identity.
Prepared by the Kingmaker Casino editorial staff.